Most Canadian sportsbooks show the Visa logo in their cashier, but acceptance and a clean first-try approval are two different things. The practical split across Visa betting sites comes down to which card you hold: a debit card pulls straight from your chequing account and usually clears instantly, a credit card can be coded as a cash advance by your issuer, and a prepaid card gets money in but rarely takes money out. Typical minimums at Canadian sportsbooks that accept Visa sit around $10–$20, with new accounts often capped near $1,000–$2,500 per day until identity checks are complete.
The Betzoid team reads cashier pages, banking terms and payout policies rather than repeating logo grids, because the details that cost you money — cash-advance coding, closed-loop withdrawal rules, card-specific bonus exclusions — live in the fine print. Below you'll find the operators we rate for card funding, followed by the card-type comparison, deposit walkthrough and decline fixes that decide whether your first attempt goes through.
Recommended Visa Betting Sites (September 2026)
Visa Debit, Credit and Prepaid Cards Compared
Debit is the default choice for most Canadian bettors, credit carries the highest hidden cost, and prepaid solves bank blocks while creating a withdrawal problem. All three carry the same 16-digit format and hit the same checkout form, so the cashier won't warn you which one you're using — your statement will, later.
| Card type | Where the money comes from | Main cost risk | Payouts back to the card | Suits |
|---|---|---|---|---|
| Visa Debit | Your chequing balance, in CAD | Low — no interest, occasional operator surcharge | Usually supported where the book offers card payouts | Routine deposits and same-card withdrawals |
| Visa Credit | Your credit line | High — cash-advance fee plus interest from day one if coded as cash-like | Often possible, but interest already charged is not reversed | Only bettors whose issuer confirms purchase coding |
| Prepaid Visa (gift, non-reloadable) | Value loaded at purchase | Moderate — activation and inactivity fees | Rarely accepted as a payout destination | Hard spending caps and avoiding bank flags |
| Reloadable or virtual Visa | Topped up from a bank account or wallet app | Moderate — load and FX fees on some programs | Sometimes, if the card supports incoming credits | Keeping betting spend off a main statement |
The payout column is where the differences matter most. A prepaid card can fund an account perfectly well, then leave you choosing a second method for winnings and waiting on extra verification. If you plan to cash out to the same card you deposited with, debit is the only option that reliably works end to end.
Avoiding Cash Advance Charges on Credit
Canadian issuers frequently treat gambling deposits as cash-like transactions, which skips the interest-free grace period. On a $200 deposit, a typical cash-advance charge of the greater of a flat fee (often around $5–$10) or a small percentage lands immediately, and interest starts accruing that day at a rate well above the purchase APR. Pay the balance a week later and the fee still stands. Before you use credit, check your cardholder agreement for the phrase "cash-like transactions" or call the number on the back and ask how gambling merchant codes are billed. If the answer is cash advance, switch to debit.
What Visa Deposits Give Canadian Bettors
The main advantage is that you set nothing up: the card already in your wallet funds the account in seconds, in Canadian dollars, with authentication your bank controls. That matters most when a line moves and you have minutes, not hours.
- Instant balance credit in most cases — the authorization and the sportsbook's confirmation typically land in under a minute, so an in-play market is still there when you return to the bet slip.
- No third-party account: unlike wallets or vouchers, there's no separate registration, no wallet-to-book transfer step and no extra password to store.
- Visa Secure (3-D Secure) verification: your bank sends a code or an app prompt, which blocks anyone holding only your card number from funding a betting account.
- Zero-liability protection and formal dispute channels apply to card transactions, giving you a route your bank administers if a charge is wrong or duplicated.
- CAD billing at books that hold Canadian-dollar balances, which avoids the 2.5% foreign-transaction markup many cards apply to USD or EUR checkouts.
Speed and familiarity are the real wins; cost advantages are neutral at best, since Interac e-Transfer is equally fee-free at most Canadian-facing books. Once funding is settled, the bigger long-term edge sits in pricing rather than payments — comparing bookmakers with the sharpest odds saves far more over a season than shaving a deposit fee.
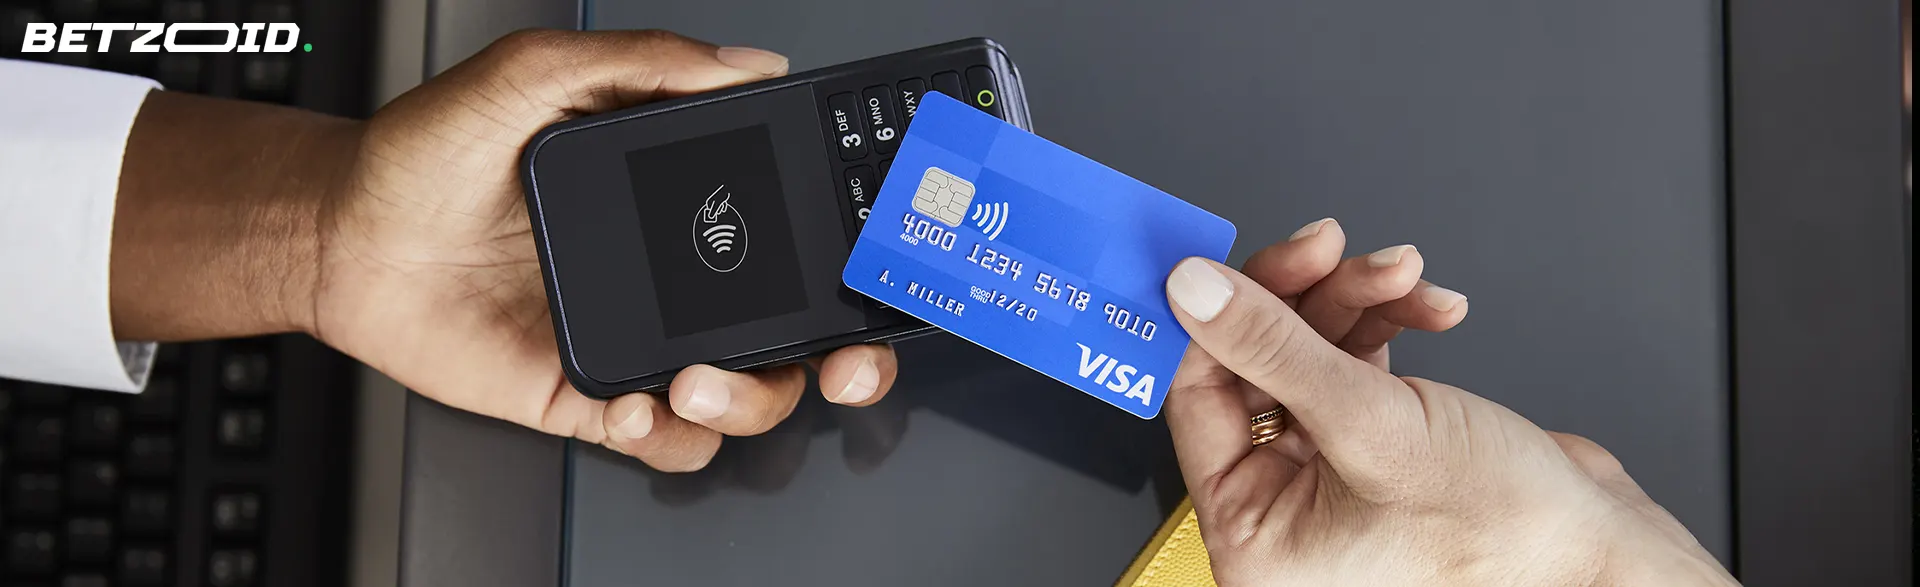
How to Deposit with Visa Step by Step
The sequence is near-identical everywhere, and the step that trips people up is almost always the billing address match, not the card details themselves.
- Open the cashier from your account menu — it is usually labelled "Deposit", "Banking" or "Wallet". Card options sometimes sit under a combined "Credit/Debit Cards" tab rather than a standalone Visa button.
- Choose Visa, then confirm whether the site is treating it as debit or credit; a few cashiers split the two because they charge differently.
- Enter the 16-digit number, expiry, CVV and the billing postal code exactly as your bank holds it, spacing included. A mismatched postal code is a silent decline in most gateways.
- Set the amount. On a site you haven't used before, the minimum Visa deposit for online sports betting is generally $10–$20 — send that first and confirm the balance updates before moving real money.
- Complete the Visa Secure prompt when your bank's screen loads: an SMS code, or an approval tap in your banking app. Don't close the tab while it redirects back.
- Check the balance, then note whether a bonus code needed to be entered before confirming — most welcome offers cannot be applied retroactively to a completed deposit.
Two Canadian wrinkles are worth flagging. Some banks require you to switch on international or gambling transactions in online banking before the first attempt clears, and provincial context shapes which operators you can use at all — bettors following the rules for sports betting in Prince Edward Island, for instance, are working with a different provincial framework than someone in Ontario.
Withdrawals Back to Your Visa Card
Deposit support does not guarantee payout support, and this is the single biggest gap among bookmakers that take Visa debit cards in Canada. Plenty of cashiers accept card funding and then list only Interac, bank wire or an e-wallet under withdrawals, which means the method you used to deposit isn't the method that pays you.
Where card payouts exist, they arrive either as a refund reversed against your original deposits or as a Visa Direct credit. Expect roughly 2–5 business days after the sportsbook approves the request, with the final posting time set by your bank rather than the operator. Interac e-Transfer is typically quicker for Canadian accounts, often clearing within a day of approval, so many bettors deposit by card and cash out by Interac by design. Add the operator's own pending period — commonly 24 to 48 hours before processing starts — and a card payout requested Friday evening realistically lands mid-week.
Before you deposit, open the withdrawal tab and read which methods appear there. Operator pages are useful for this: our Ivibet review sets out the banking section alongside the rest of the offer, so you can see the payout options rather than assuming they mirror the deposit list.
Why Payouts Cap at Your Deposit Total
Licensed operators run closed-loop refunds for anti-money-laundering reasons: money returns to its source before it goes anywhere else. Deposit $400 by card and the first $400 you withdraw can usually be reversed back to that card, while anything above it — your actual profit — routes through a verified bank account, Interac or an e-wallet. It isn't a penalty, and it isn't a sign of a bad book; it's standard licensing practice. The practical consequence is simple: have a second, verified payout method registered before you win, or your withdrawal sits waiting on documents.
Fees, Minimums and Daily Deposit Limits
Most Canadian-facing sportsbooks charge nothing on card deposits, so the costs that appear on your statement usually come from your issuer or the card program, not the operator. The table sets out where each charge originates and what to verify first.
| Item | Typical range | Charged by | What to check |
|---|---|---|---|
| Minimum deposit | $10–$20 | Operator | Whether the bonus minimum is higher than the cashier minimum |
| Daily cap, new account | $1,000–$2,500 | Operator | When the cap lifts — usually after ID verification |
| Operator card fee | 0%, occasionally 2–3% | Operator or payment processor | A fee line shown on the confirmation screen before you submit |
| Cash-advance charge | Flat fee plus interest from day one | Your credit card issuer | How your agreement codes gambling merchants |
| Foreign transaction markup | About 2.5% | Your bank | Whether the book holds balances in CAD or converts |
| Withdrawal minimum | $20–$50 | Operator | Free withdrawals per month before a fee applies |
No-fee Visa deposits at Canadian betting sites are the norm, which makes the currency line the one most worth checking. A 2.5% conversion markup on a $500 deposit costs $12.50 before you've placed a bet — more than any realistic cashier surcharge. Daily caps matter in a different way: if you intend to fund $3,000 for a playoff run, complete verification first, because hitting a new-account ceiling mid-deposit leaves you split across two methods and two clearing times.
Why a Visa Card Gets Declined at Checkout
A rejection at the cashier almost always comes from your bank, not the sportsbook, and the site rarely tells you which reason applied. These are the causes worth ruling out in order:
- Issuer policy on gambling merchant codes — some Canadian banks block the category outright on certain cards, and no amount of retrying changes it until you speak to them.
- Billing details mismatch — a postal code, street number or expiry that doesn't match the bank's record fails the address check even though the card is perfectly valid.
- Fraud scoring on a first transaction — a new merchant, an unfamiliar amount or a VPN connection can trigger a hold that clears once you approve the attempt in your banking app.
- Limits you've already hit — the operator's daily cap, a per-transaction ceiling, or your own card's available balance after pending authorizations.
- Card type restrictions — a non-reloadable prepaid Visa sometimes fails because the gateway requires a card that can also receive credits.
If the block is a bank policy rather than a one-off flag, repeated attempts can freeze the card entirely. Switching funding rails is often faster than arguing: Interac is the obvious Canadian alternative, and operators built around other payment types — the kind covered in our Gamdom review — sidestep card networks altogether.
Checks Before Your First Deposit
Five minutes of preparation prevents most failed transactions. Confirm the operator is licensed and open to players in your province. Check the withdrawal tab for card payouts before you fund, and register a backup method for winnings above your deposit total. Verify your identity early so the new-account daily cap lifts before you need the headroom. Call your issuer if you're using credit and ask directly whether gambling transactions are billed as purchases or cash advances. Finally, make a minimum deposit first: if $10 or $20 clears cleanly and appears in the balance, a larger amount will behave the same way on the same card.
Card funding comes down to three decisions: debit over credit to keep cash-advance charges off your statement, a CAD-denominated book to avoid the 2.5% conversion markup, and a verified second payout method because card withdrawals typically cap at what you deposited and run 2–5 business days. Use the comparison above to match your card type to the way you actually want to be paid, then make one small test deposit before committing a real bankroll. Set a deposit limit in your account settings while you're in the cashier — it takes the same minute as entering your card details, and it's the one control that keeps the card in your wallet working for you.